Log into your student loan account. Look at the balance. It’s six figures for people who borrowed to study over the last decade or so, and it sits there glowing at you like a verdict.
Here is the thing nobody told you at the open day: for many of the people who borrowed it, that number is largely made up.
It is not fraudulent, nor is it an accident. The gap between what the screen shows and what you will actually repay is built into the architecture of the whole system, on purpose, and once you understand it, student loans stop being frightening and start being something considerably stranger and more interesting.
The Loan That Was Never Really a Loan
A normal loan is concerned with how much was borrowed in the first place. Borrow more, owe more, repay more. The logic is tight and unforgiving.
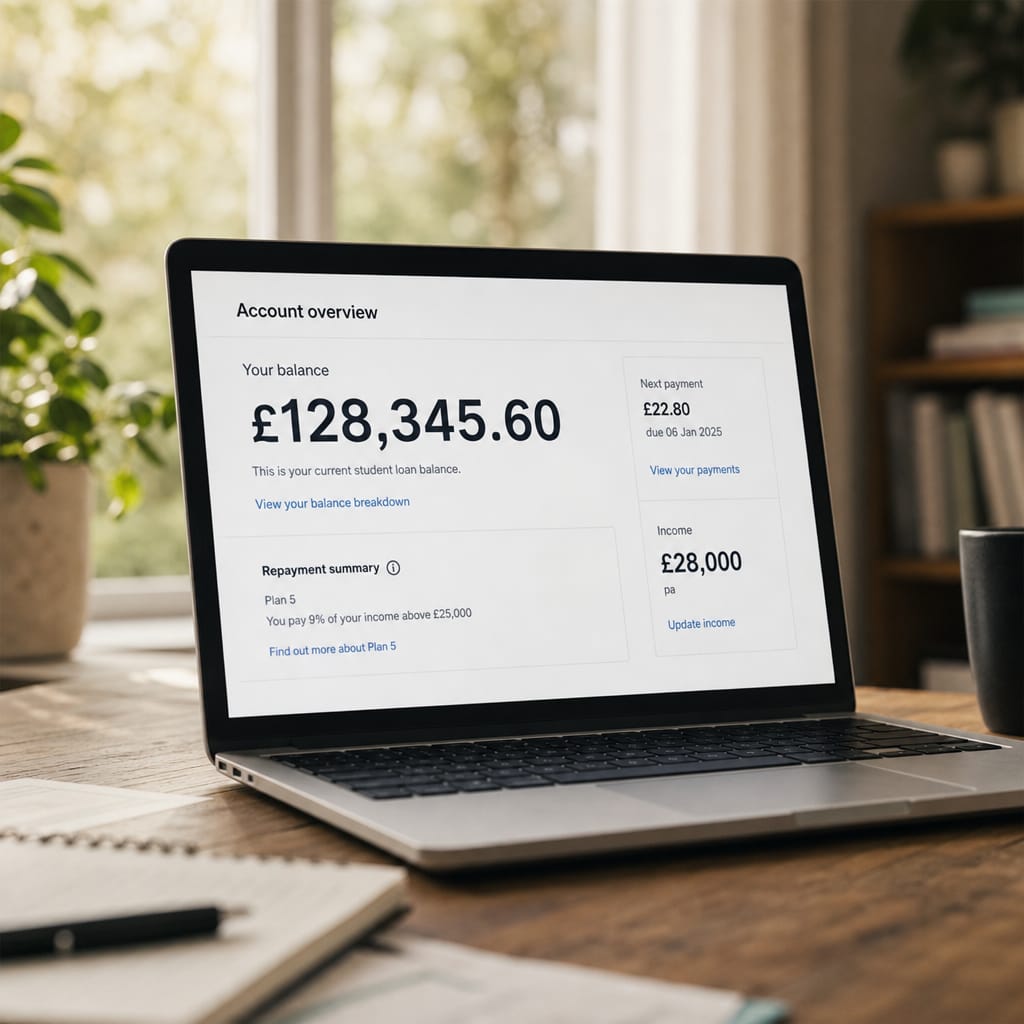
In contrast, the UK student loan does not work like this. What is repaid each month is not linked to the balance, rather it is set entirely by salary. Under the current system (Plan 5, for most students starting since 2023), borrowers repay 9% of whatever they earn above £25,000 a year, and nothing at all below that threshold.
Earn £28,000? You repay 9% of £3,000, which comes to around £270 a year, just over £22 a month. Earn £24,500? You repay zero, regardless of whether your outstanding balance is £30,000 or £130,000.
The balance on the screen is not a bill. It is a ceiling that your monthly salary-linked payments are slowly pecking at, and for many people, they will never peck through it.
The Expiry Date Hiding in the Small Print
What is genuinely odd about this is the write-off. After a set period — 30 years for most post-2012 borrowers, 40 years under the newer Plan 5 rules — whatever is left on the balance is cancelled. Gone. No bailiffs, no black mark, just a quiet administrative deletion.
The Institute for Fiscal Studies has estimated that under older loan arrangements the majority of graduates were on track to have a significant portion of their debt wiped without ever repaying it in full. Under Plan 5 the longer repayment period and lower repayment threshold shift more of the burden onto mid-range earners, but the basic logic holds: the system was designed with mass partial write-off baked in, and the Treasury budgets for it. Not a glitch, not a generous mistake. It is how the sums are supposed to balance.
What this means in practice is that the loan functions, for most borrowers, far less like a mortgage and far more like an additional income tax rate. A graduate tax, if you like, that runs for three or four decades and then expires.
Why Borrowing More Sometimes Changes Nothing
Here is where things get properly counterintuitive. Say you do a Master's degree and take out an extra £15,000 on top of your undergraduate loan. This is the point at which you expect your lifetime repayments to rise accordingly. For a high earner, they probably will. But for a graduate on a middling salary – someone whose repayments were already going to fall short of clearing the original balance – that extra £15,000 sits on top of a number that was already heading for the write-off bin. You are adding to a fiction. Your monthly payments stay the same (still 9% of earnings above the threshold), your write-off date stays the same, and the only thing that changes is the figure you have to look at when you log in.
This is the reason financial advisers who understand the system often say: do not rush to make voluntary overpayments. Every pound you throw at the balance is a pound that might have been written off for free in year 39 anyway.
Plan 2 and Plan 5 Side by Side
Most graduates now in their twenties or thirties are on one of two plans. Plan 2 covers students from England who started a course between 1 September 2012 and 31 July 2023, and students from Wales who started on or after 1 September 2012. Plan 5 covers students from England who started on or after 1 August 2023. Both take 9% of income above a threshold, but the thresholds, the interest and the write-off date are different, and those three differences decide how much of the balance anyone actually pays.
| Plan 2 | Plan 5 | |
|---|---|---|
| Who it covers | England: courses started 1 September 2012 to 31 July 2023. Wales: started on or after 1 September 2012 | England: courses started on or after 1 August 2023 |
| Repayment threshold | £29,385 a year | £25,000 a year |
| Repayment rate | 9% of income above the threshold | 9% of income above the threshold |
| Interest | RPI to RPI plus 3%, depending on income (currently capped at 6%) | RPI only |
| Written off | 30 years after the April you were first due to repay | 40 years after the April you were first due to repay |
How the Interest Is Worked Out
Interest is linked to the Retail Prices Index. The rate is set on 1 September each year using the RPI figure from the previous March, and the Student Loans Company adds interest to the balance every month. On Plan 5 the rate is RPI only. On Plan 2 it is RPI plus 3% while you study, then a sliding scale once you leave: RPI alone on lower incomes, rising to RPI plus 3% for higher earners, with a government cap that currently holds the maximum at 6%.
RPI is an odd yardstick to use. It lost its status as a National Statistic in 2013, and the Office for National Statistics says plainly that it does not think RPI is a good measure of inflation and discourages its use. Because it usually runs above other measures, a balance can keep growing for years after repayments start, simply because the interest added each month outpaces what a modest salary chips away.
Why the Balance Rarely Shows Up Where You Expect
Student loans are not normally reported to the credit reference agencies, so they do not sit on your credit file the way a credit card or car finance agreement does. They can still matter to a mortgage lender, because the monthly repayment comes out of your pay and so reduces what you can afford.
The national accounts treat them in a similar spirit. Since the Office for National Statistics changed its approach in 2018, the part of each year’s lending that is not expected to be repaid is counted as government spending when the money is lent, instead of appearing decades later when balances are written off. That is also why “graduate tax” is the comparison people keep reaching for: repayments come through PAYE like tax and stop when a time limit runs out. It has never been called a tax, which is often said to be partly because money raised as tax goes to the Treasury rather than being set aside for universities.
Should You Make Extra Repayments?
For many borrowers, no. If your balance is unlikely to be cleared before the write-off date, a voluntary payment is money you would never otherwise have had to hand over. The Department for Education’s own forecasts expect 55% of full-time undergraduates starting in 2025/26 to repay in full, which also means a large minority will not. Higher earners who are on course to clear the balance are the exception, because paying early can cut the total interest they pay. The right answer depends on your likely earnings over several decades, so work it through with the official repayment figures rather than guessing.
The Genuinely Worth-Knowing Part
The system is not perfect or painless. Higher earners, particularly those going into medicine, law, and finance will repay the full amount and often more thanks to interest. The write-off timescale has lengthened. The threshold above which you repay has been frozen in ways that quietly pull more people in.
But for those anxious about that six-figure number on the screen, the most useful thing to know is this: many of them are not looking at a debt in any traditional sense. What they are looking at is a commitment to pay a small extra percentage of their salary for a few decades, with an expiry date attached. The number itself – the one that feels so solid and so damning – is largely a placeholder for a sum they were probably never going to hand over anyway.
Updated October 2026: this article now includes material from two related articles we have retired, with current Plan 2 and Plan 5 figures from GOV.UK.
FAQ
How much do you repay on a Plan 5 student loan?
The rate that borrowers on Plan 5 repay is 9% of the amount that they earn above £25,000 each year, and nothing below that threshold. So someone on Plan 5 who has income of £28,000 will pay 9% of £3,000, which is around £270 per year, or just over £22 per month. This amount does not change with the outstanding balance of the loan.
When is a student loan written off?
The remaining balance on the amount borrowed is written off after a set period of time. This is 30 years after April of the first year of repayment for Plan 2 borrowers and 40 years for Plan 5 borrowers. This is an administrative write off with no involvement of bailiffs and no adverse credit entry, and the Treasury budgets for it.
Should you make voluntary overpayments on a student loan?
For many borrowers, no. If you’re unlikely to clear your balance by the write-off date, paying extra would just be throwing money down the drain. However, some higher earners who are on course to repay in full could reduce the amount of interest they pay by paying early.
What is the difference between Plan 2 and Plan 5?
Both plans use 9% of income above a threshold, but the amounts and terms are different. Plan 2 uses a threshold of £29,385, interest rate of RPI to RPI + 3%, and write-off after 30 years. Plan 5 uses a threshold of £25,000, interest rate of RPI only, and write-off after 40 years. This plan covers English students starting on or after 1 August 2023.